
Key Takeaways
- Older paid-off vehicles eliminate monthly loan payments, which can outweigh higher repair costs for many drivers.
- Insurance premiums are typically lower on older vehicles, reducing one of the largest ongoing ownership expenses.
- A single major repair on an older car often still costs less than several months of new-car payments.
- Safety technology gaps and parts availability are legitimate reasons to consider replacing an aging vehicle.
- The right decision depends on the vehicle's condition, your budget, and how reliable your transportation needs to be.
No monthly loan payment reduces fixed costs
A paid-off vehicle eliminates a recurring obligation that typically runs several hundred dollars per month on a financed replacement. That savings alone often exceeds a year's worth of routine repairs on an older car.
Lower insurance premiums on older vehicles
Without a lender requiring full coverage, owners can adjust their policy to match the vehicle's actual value. This regularly produces meaningful monthly savings compared to insuring a financed newer car.
Depreciation has already occurred
New and near-new vehicles lose value quickly in the early years. An older vehicle's value has largely stabilized, so repair spending is not competing against a steep ongoing loss in asset value.
Known service history reduces uncertainty
A vehicle you have owned and maintained gives you direct knowledge of what has and has not been serviced. That information is genuinely useful when assessing future reliability.
Avoiding new registration and transaction costs
Purchasing a replacement vehicle involves title transfer fees, sales tax in most states, and potentially dealer fees. These upfront costs are easy to overlook when comparing the sticker price of a replacement.
Repair frequency tends to increase with age
Components wear out in clusters as a vehicle ages. A car that needed minimal work at 80,000 miles may require noticeably more attention past 120,000 miles, making costs less predictable.
Older vehicles lack current safety technology
Features like automatic emergency braking, rearview cameras, and lane-departure warnings are absent on most vehicles older than a decade. These systems have a measurable effect on crash avoidance.
Parts availability can become an obstacle
For certain makes and models, replacement parts become scarce as production ends. Longer wait times and higher costs from specialty suppliers can make repairs less practical over time.
Reliability risk is harder to predict
Even a well-maintained older vehicle can experience unexpected failures that leave a driver stranded. The potential for unplanned downtime is a real cost for anyone who depends on consistent transportation.
Fuel efficiency may lag newer alternatives
Older engines, particularly those from before widespread adoption of direct injection and advanced transmission technology, often consume more fuel per mile than comparable newer models.
Our Verdict
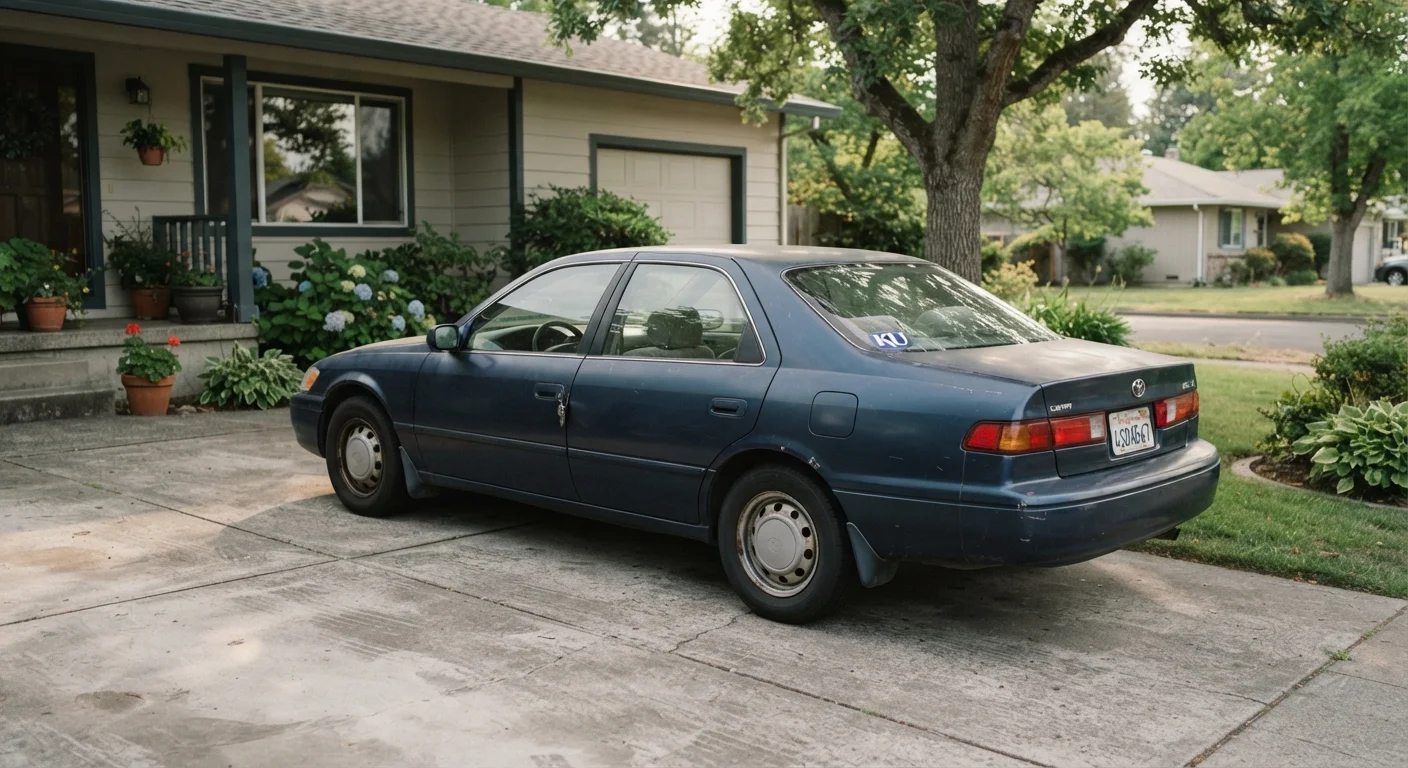
Keeping an older vehicle is financially sound when repair costs remain below what a replacement would cost monthly, the car is mechanically sound, and your situation allows for occasional inconvenience. Moving on makes more sense when cumulative repairs start approaching the vehicle's market value, critical safety systems are failing, or parts availability has become a genuine obstacle.
Drivers with a paid-off vehicle in reasonable mechanical condition who want to minimize fixed monthly transportation costs.
How to think about the keep-or-replace question
The decision to hold onto an aging vehicle or replace it is rarely as simple as a single repair bill. It involves comparing two sets of ongoing costs against each other, not evaluating a one-time expense in isolation.
A common starting point is the so-called "repair vs. replace" threshold. If a repair estimate approaches or exceeds the vehicle's current market value, many drivers assume replacement is the logical move. That framing is too blunt. A car worth $4,000 that needs $2,500 in repairs may still be cheaper to fix than to replace, because the alternative is not free. A replacement vehicle carries its own costs: a down payment, monthly loan payments, higher insurance premiums on a newer model, and registration fees tied to a higher assessed value.
A more useful comparison is to stack the annualized cost of keeping the current vehicle, including expected maintenance and repairs, against the annualized cost of switching. For help tracking those expenses over time, see strategies for managing car ownership costs long term.
Market value is a starting point, not a verdict
Vehicle valuation tools give you a rough market estimate, but condition, mileage, and local demand all affect what your car is actually worth to you as transportation. A car with a low market value that runs reliably may have more practical value than its resale price suggests. Use market value as one data point in the comparison, not the deciding factor.
The case for keeping an older vehicle
Older vehicles that are paid off give their owners a structural financial advantage: no monthly loan obligation. That absence of a fixed payment changes the math considerably.
No monthly loan payment reduces fixed costs
A paid-off vehicle eliminates a recurring obligation that typically runs several hundred dollars per month on a financed replacement. That savings alone often exceeds a year's worth of routine repairs on an older car.
Lower insurance premiums on older vehicles
Without a lender requiring full coverage, owners can adjust their policy to match the vehicle's actual value. This regularly produces meaningful monthly savings compared to insuring a financed newer car.
Depreciation has already occurred
New and near-new vehicles lose value quickly in the early years. An older vehicle's value has largely stabilized, so repair spending is not competing against a steep ongoing loss in asset value.
Known service history reduces uncertainty
A vehicle you have owned and maintained gives you direct knowledge of what has and has not been serviced. That information is genuinely useful when assessing future reliability.
Avoiding new registration and transaction costs
Purchasing a replacement vehicle involves title transfer fees, sales tax in most states, and potentially dealer fees. These upfront costs are easy to overlook when comparing the sticker price of a replacement.
Depreciation is another factor that works in favor of the older-vehicle owner. New cars lose a significant portion of their value in the first few years. An older vehicle has already absorbed that loss, so any money spent maintaining it goes toward preserving transportation capacity rather than chasing a moving depreciation curve.
Insurance costs tend to be lower as well. Lenders on financed vehicles typically require comprehensive and collision coverage. Owners of paid-off older cars can often carry liability-only coverage or raise deductibles, reducing monthly premiums. Review your coverage periodically, since the right level of protection changes as a vehicle ages.
Familiarity also has practical value. When a driver knows a vehicle's quirks, service history, and maintenance gaps, there are fewer surprises than with an unfamiliar used replacement. For context on what routine upkeep actually involves, see routine maintenance every car owner should understand.
The case for moving on
There are genuine circumstances where continuing to invest in an older vehicle stops making sense.
Repair frequency tends to increase with age
Components wear out in clusters as a vehicle ages. A car that needed minimal work at 80,000 miles may require noticeably more attention past 120,000 miles, making costs less predictable.
Older vehicles lack current safety technology
Features like automatic emergency braking, rearview cameras, and lane-departure warnings are absent on most vehicles older than a decade. These systems have a measurable effect on crash avoidance.
Parts availability can become an obstacle
For certain makes and models, replacement parts become scarce as production ends. Longer wait times and higher costs from specialty suppliers can make repairs less practical over time.
Reliability risk is harder to predict
Even a well-maintained older vehicle can experience unexpected failures that leave a driver stranded. The potential for unplanned downtime is a real cost for anyone who depends on consistent transportation.
Fuel efficiency may lag newer alternatives
Older engines, particularly those from before widespread adoption of direct injection and advanced transmission technology, often consume more fuel per mile than comparable newer models.
Reliability risk is one factor that numbers alone do not fully capture. If a vehicle's failures are unpredictable and your daily life depends on dependable transportation, the cost of a breakdown goes beyond the repair bill. A driver who cannot afford to miss work or whose safety is affected deserves to weigh that risk honestly.
Safety technology has advanced considerably in the past decade. Automatic emergency braking, lane-keeping assistance, and blind-spot monitoring are now standard or widely available on many vehicles. Older models do not have these systems, and that gap is worth factoring in, particularly for high-mileage highway drivers.
If you do decide to replace, the full process for buying a used car covers the steps from setting a budget through completing the title transfer. Before purchasing any used vehicle, reviewing its history is worth the time. red flags to watch for when reviewing a car history report explains what accident records, title issues, and odometer discrepancies actually mean.
Practical signals that tip the decision
Rather than waiting for a single dramatic repair, there are patterns that indicate a vehicle is becoming difficult to justify keeping.
- Repairs are becoming more frequent, not just more expensive. A car that needed one significant repair two years ago and now needs two or three per year is showing a different pattern.
- The failed or failing components are in core systems: engine, transmission, or suspension. Cosmetic or minor electrical issues are different from structural failures.
- Parts are getting harder to source. Some older models reach a point where components are discontinued or available only through specialty suppliers, which increases both cost and repair time.
- The vehicle has failed a state emissions or safety inspection and the required repairs are extensive.
Conversely, a vehicle that has had consistent preventive care, has a documented service history, and has not yet entered a pattern of cascading failures is often worth maintaining. common maintenance misconceptions addresses some of the beliefs that lead owners to under-maintain or unnecessarily abandon otherwise sound vehicles.
Running the numbers
A straightforward way to test the decision is to calculate what keeping the vehicle costs per month over the past 12 months, including all repairs, routine maintenance, insurance, and registration. Compare that total to what a replacement would cost monthly, factoring in loan payments, higher insurance, registration, and any expected maintenance on the replacement.
$700+
Average monthly new-car payment in the US
Federal Reserve and industry tracking data have placed the average new-vehicle monthly payment above $700 in recent years, a figure that shapes the replacement cost baseline.
~$1,500
Estimated average annual repair cost for older vehicles
Consumer expenditure surveys and automotive industry data suggest drivers of older vehicles typically spend between $1,000 and $2,000 per year on unplanned repairs, though this varies significantly by make and condition.
If the current vehicle's monthly average is lower, and there is no strong reliability or safety concern, continuing to maintain it is generally the more cost-effective path. If the numbers are close or the replacement comes out ahead, and the current vehicle's condition is declining, replacement becomes more defensible.
This framework does not account for every variable. A driver with an emergency fund large enough to absorb an unexpected repair is in a different position than one who would need to finance an unplanned expense. Personal financial cushion matters as much as the raw cost comparison.