
Key Takeaways
- A salvage or rebuilt title affects both resale value and your ability to get full insurance coverage.
- Odometer rollback is one of the most common forms of used-car fraud in the US.
- Multiple ownership changes in a short period can signal unresolved mechanical problems.
- Accident records vary in detail; always cross-reference with a pre-purchase inspection.
- Lien records on a vehicle history report mean you could inherit someone else's debt.
Summary
18 items · 20 to 40 minutes
What a vehicle history report tells you
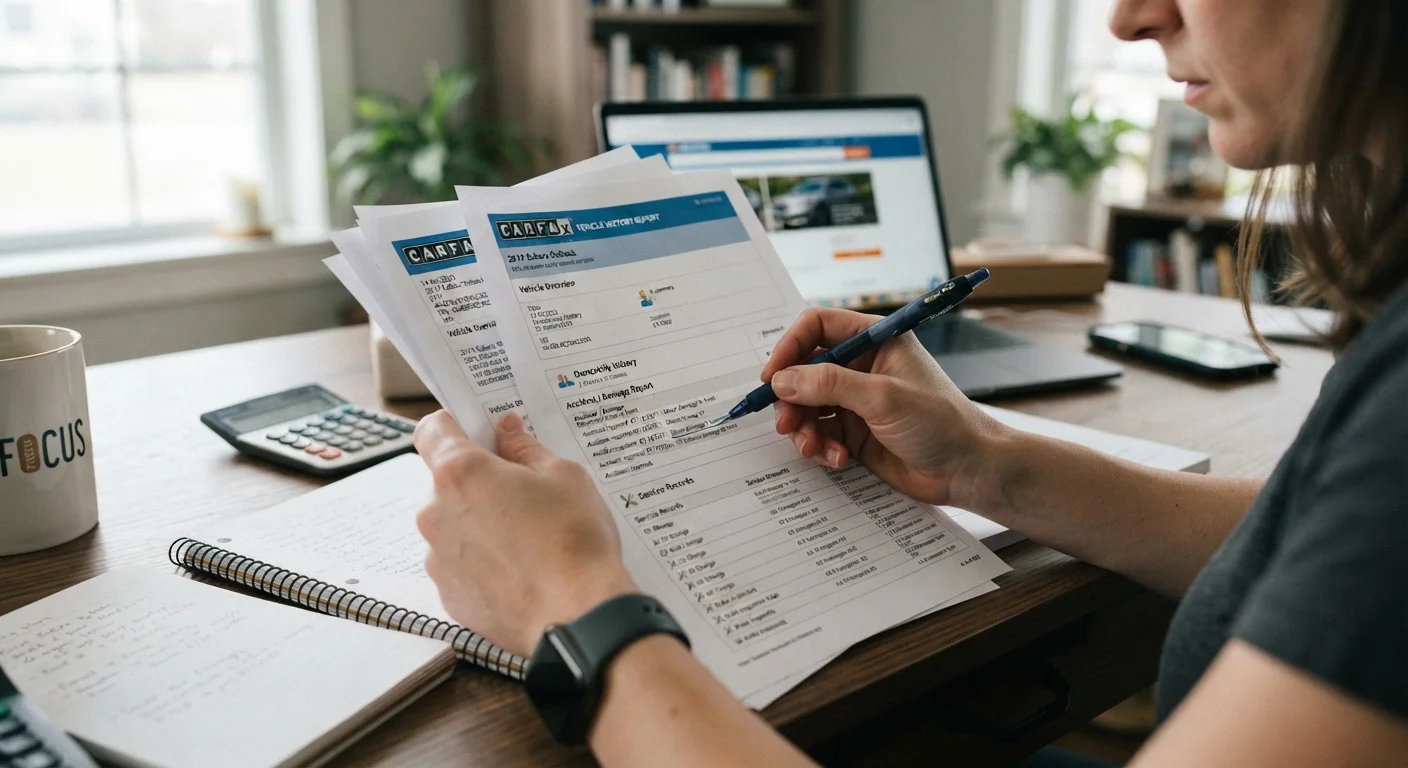
A vehicle history report pulls data from state DMV records, insurance claims, auction records, and reported service history to give a picture of what a car has been through before it reaches you. The two most widely used report providers in the US are CARFAX and AutoCheck, and many dealers provide one or both at no charge. If a private seller refuses to share a report, treat that refusal as a signal.
The report does not catch everything. Accidents that were never reported to an insurer, repairs done in cash at independent shops, and flood damage in states with poor disclosure laws can all go unrecorded. That is why a vehicle history report works best as a filter, not a final verdict. Pair it with a pre-purchase mechanical inspection by a qualified technician before committing. See the full process in our step-by-step used car buying guide.
Title and ownership status
Accident and damage history
Odometer and mileage accuracy
Service and inspection records
Final cross-checks before deciding
How to act on what you find
Finding a red flag does not automatically mean walking away. Some issues, like a single minor fender-bender with documented repairs, may have little practical effect. Others, like a salvage title or odometer discrepancy, carry financial and safety consequences that rarely resolve cleanly.
A clean report is not a guarantee
Vehicle history reports only contain events that were reported to participating sources. A car that was in a serious accident and repaired privately, or flooded in a state with weak disclosure rules, may show no damage record at all. Never skip a physical pre-purchase inspection with a qualified mechanic, even when the report looks clean.
Title status has direct implications for insurance. A vehicle with a rebuilt title is often difficult to insure for comprehensive and collision coverage, and some insurers decline it entirely. Before purchase, contact your insurer to confirm what coverage they will offer on any vehicle with a branded title. For a detailed explanation of title categories, see our guide on car title types and what each status means.
Unresolved liens are a separate concern. If the report shows an open lien and the seller cannot provide a lien release letter or payoff documentation, do not complete the purchase. In many states, the lienholder retains a legal claim on the vehicle even after you buy it, which means you could lose the car or be required to pay off another person's loan to keep it. These scenarios fall squarely into the category of hidden ownership costs that catch first-time buyers off guard. Long-term cost management starts with getting the title right at purchase. Our guide to managing car ownership costs over the long run covers what comes next once you own the vehicle.