

Key Takeaways
- Paying more than the minimum each month cuts total interest and shortens your repayment timeline significantly.
- The avalanche and snowball methods are two structured approaches to targeting multiple debts at once.
- Refinancing or consolidating high-interest debt can reduce the rate you pay, but terms and fees matter.
- Directing windfalls like tax refunds or bonuses toward debt can compress a multi-year payoff schedule.
- Balancing debt payoff with a small emergency reserve helps prevent new debt from undoing your progress.
Why paying down debt faster is worth the effort
Carrying debt costs money every month beyond the principal you borrowed. Interest accumulates whether you make progress or not, so the longer a balance stays on the books, the more you ultimately pay. Paying only the minimum each month can stretch a balance for years and multiply the total cost well beyond the original loan amount.
The strategies below are not ranked or prescribed for any individual situation. They are approaches many people use, each with its own logic and trade-offs. A qualified financial adviser can help you match them to your specific income, expenses, and debt types. This article is general financial information, not personalized advice.
Pay more than the minimum whenever possible
Every loan payment splits between interest and principal. When you pay only the minimum, most of the early payment covers interest, and the principal shrinks slowly. Adding any amount above the minimum, even a modest one, accelerates how fast the principal drops and reduces the interest that compounds on top of it.
Before doing this with a loan, check whether your lender applies extra payments to principal directly or to future scheduled payments. Some lenders require you to specify that extra funds go toward principal reduction.
Adding even a modest amount above the minimum accelerates how fast principal drops.
Use the avalanche method to cut total interest paid
The avalanche method means directing extra payments to the debt with the highest interest rate while paying minimums on all others. Once that balance reaches zero, the freed-up payment amount rolls to the next highest-rate debt. Over time, this approach reduces the total interest paid across all accounts, though it can take longer to see a full balance disappear if the highest-rate debt is also the largest.
Whether a debt is secured or unsecured also affects how you should think about prioritization, since secured debts carry collateral consequences that unsecured ones do not.
The avalanche method reduces total interest paid across all accounts over time.
Use the snowball method to build momentum
The snowball method targets the smallest balance first, regardless of interest rate. Paying off a smaller account quickly frees up its minimum payment and removes one creditor from the picture. Many people find this satisfying enough to stay consistent with a payoff plan, which matters because consistency over months and years is what produces results.
The trade-off is that if the smallest balance also carries a low rate, you may pay more total interest than you would with the avalanche approach. Both methods work; the question is which one you will actually stick with.
Consistency over months and years is what produces debt payoff results.
Refinance or consolidate to lower your interest rate
If your credit profile has improved since you took on a debt, you may qualify for a lower interest rate through refinancing. A lower rate means more of each payment reduces principal rather than covering interest costs. Debt consolidation, where multiple balances are combined into a single loan, can have the same effect if the consolidated rate is lower than what you were paying on the individual accounts.
Read the terms carefully. Origination fees, prepayment penalties, and a longer repayment term can offset the benefit of a lower rate. Extending the term lowers the monthly payment but may increase total interest paid over the life of the loan.
A lower interest rate means more of each payment reduces principal, not interest costs.
Apply windfalls and irregular income directly to debt
Tax refunds, work bonuses, and unexpected cash can make a disproportionate dent in a balance if applied immediately rather than absorbed into general spending. A single lump-sum payment reduces the principal on which future interest is calculated, compressing the remaining repayment schedule. Making a deliberate plan before windfall money arrives helps avoid the common pattern of spending the funds before a decision is made.
A single lump-sum payment reduces the principal on which all future interest is calculated.
Negotiate with creditors for better terms
Creditors sometimes adjust interest rates, waive late fees, or restructure payment terms for borrowers who ask. This is more common with credit card issuers than with installment lenders, but it is worth understanding the process. What is generally possible when negotiating with creditors covers realistic outcomes and how to approach the conversation.
No outcome is guaranteed, and a creditor is under no obligation to change your terms. However, a lower rate or waived fee on an existing balance immediately changes the math on how long payoff will take.
A lower rate or waived fee on an existing balance changes the payoff math immediately.
Build a small emergency reserve alongside debt payoff
Putting every available dollar toward debt can backfire if an unexpected expense forces you to borrow again. A small cash reserve, enough to cover a few hundred to a few thousand dollars of unplanned costs, reduces the risk that a car repair or medical bill restarts the debt cycle. The trade-off between saving and paying down debt depends on interest rates, income stability, and how much cushion already exists.
The reserve does not need to be large at first. Even a modest buffer changes the odds that a single surprise expense sends you back to a credit card.
A small cash reserve reduces the risk that one surprise expense restarts the debt cycle.
Putting it all together
None of these approaches requires perfection. Small, consistent moves compound over time. Even an extra $50 a month applied to principal reduces the interest that accrues the following month, which means a slightly larger share of each subsequent payment goes to principal. That cycle works in your favor once it starts.
If you have money available and are unsure whether to pay down debt or build savings first, the interest rate on your debt is usually the clearest guide. How to think through the savings versus debt trade-off explains that framework in more detail. And if you want to see how a structured plan looks on paper, a practical debt repayment example walks through a concrete scenario from start to finish.
Track your progress in writing
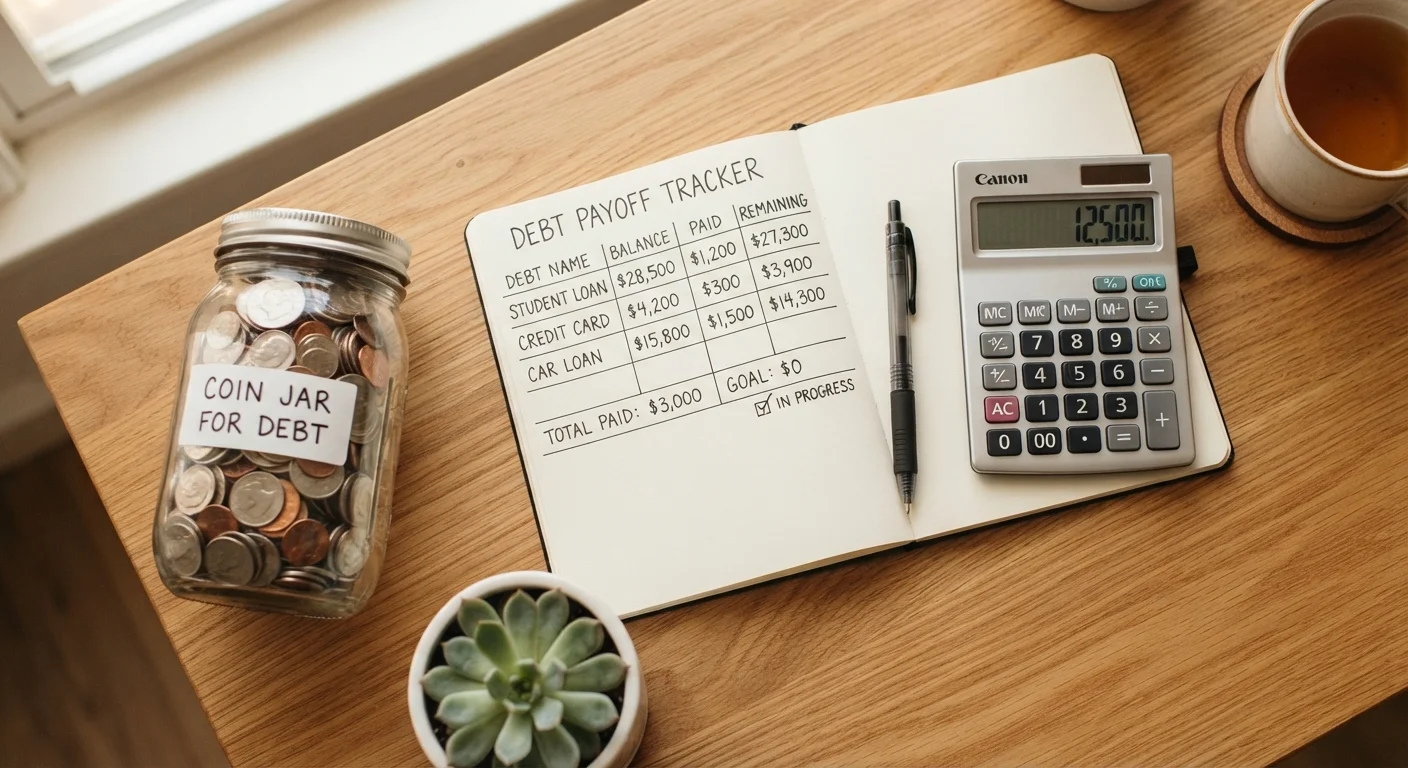
Writing down balances, interest rates, and monthly payments on a single page makes the overall picture visible and easier to manage. Updating that record each month, even briefly, helps you catch errors on statements and see that the numbers are actually moving. Small, visible progress is one of the more reliable ways to stay with a repayment plan over time.
This article is for general informational purposes only and does not constitute personalized financial, tax, or legal advice. Consult a licensed financial professional before making decisions about your debt repayment strategy.