

Key Takeaways
- High-interest debt almost always costs more than savings can earn, so paying it down first is usually the stronger move.
- A small emergency fund should exist before you put all windfall money toward debt payoff.
- Splitting a windfall between debt and savings is a reasonable middle path when both needs are real.
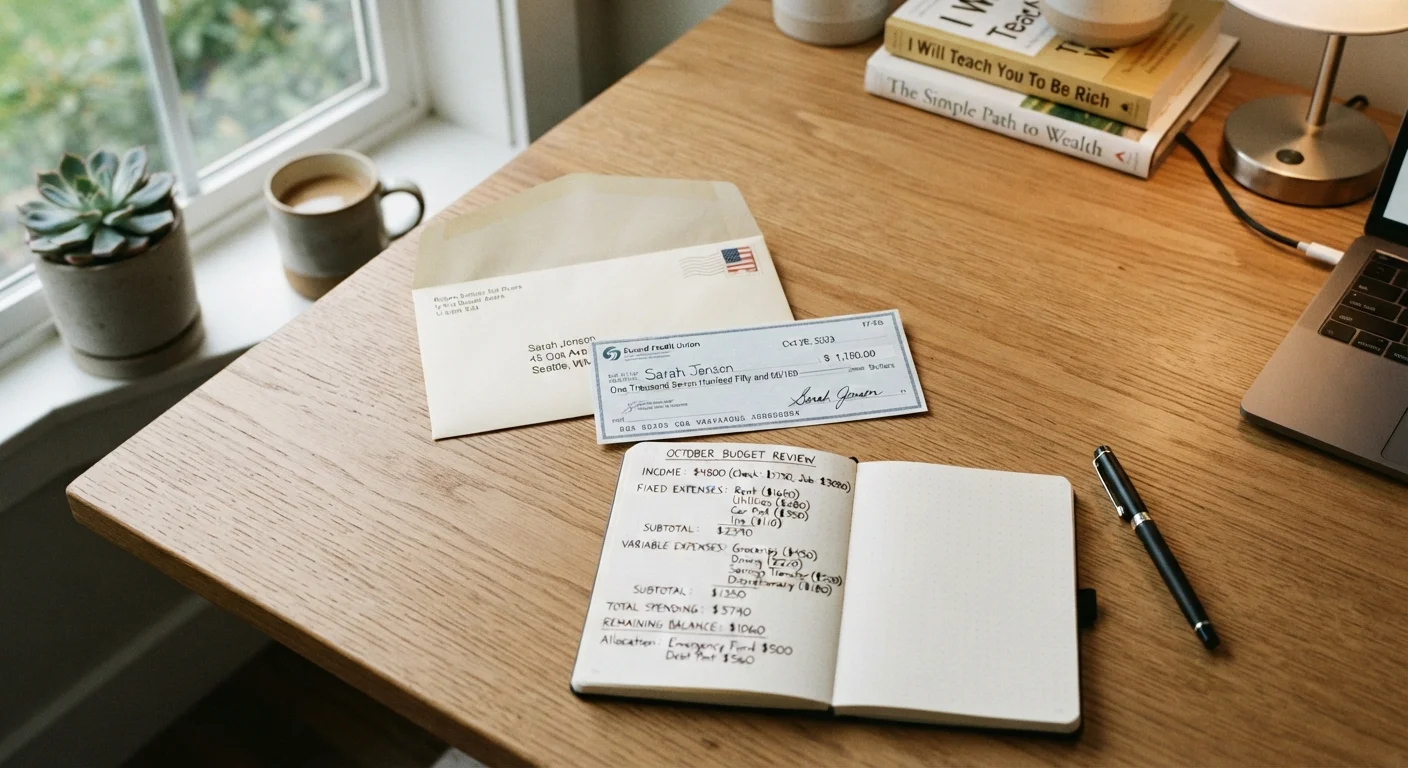
- Writing a specific allocation plan before the money arrives reduces impulsive spending.
- The right split depends on your interest rates, existing reserves, and income stability.
Why windfalls disappear without a plan
A tax refund, an inheritance, a work bonus: each one arrives with genuine potential to move your financial situation forward. What typically happens instead is that the money blends into day-to-day spending and vanishes within two or three months, leaving little changed.
The reason is not weak willpower. Unplanned money has no assigned purpose, so it fills whatever gap is most visible at the moment. A plan written before the deposit clears prevents that drift. What a debt repayment plan looks like on paper shows how to structure that thinking concretely.
This is general information, not personal advice
The guidance here covers general financial principles and is not tailored to your individual situation. Interest rates, tax implications, and the right balance between debt and savings vary widely by person. A licensed financial adviser or nonprofit credit counselor can help you apply these ideas to your specific circumstances.
The debt-versus-savings trade-off in plain terms
The central question is whether paying down debt or adding to savings produces a better financial outcome. The math is straightforward: if a debt carries a 20% interest rate and a savings account earns 5%, every dollar kept in savings rather than applied to the debt costs 15 cents per year in net interest. High-interest consumer debt almost always wins the comparison.
The exception is when you have no liquid savings at all. Paying off debt completely while holding zero reserves means the next financial surprise, a medical bill, a car repair, goes straight back onto a credit card. A minimal cash buffer protects the progress you make with a lump-sum payment.
Strategies for getting out of debt faster covers how lump-sum payments interact with refinancing and other payoff approaches.
Six practices for allocating a windfall deliberately
These approaches apply whether the windfall is $500 or $50,000. The scale changes; the logic does not.
Calculate the true cost of each debt before allocating any windfall funds.
Knowing the annual percentage rate (APR) on each balance tells you what carrying that debt actually costs per year. Without that number, any allocation decision is a guess.
Build or top up a small emergency fund before eliminating all debt.
Putting every windfall dollar toward debt and leaving no liquid reserve means one unexpected car repair sends you back to the credit card. A starter emergency fund of roughly one month of essential expenses breaks that cycle.
Write a specific dollar allocation plan before the money hits your account.
Money that sits unplanned in a checking account tends to absorb into daily spending within weeks. A written plan gives the windfall a job the moment it arrives. See how pausing before spending reduces financial regret over time.
Match allocation weight to interest rate, not to balance size.
A common mistake is paying off the smallest balance first purely for the psychological win, while a higher-rate debt grows faster in the background. The math generally favors targeting the costliest debt first, though the full savings versus debt trade-off has more nuance depending on your situation.
Treat retirement account contributions as a category, not an afterthought.
If your employer matches retirement contributions and you are not yet capturing the full match, every dollar of windfall not directed there is a partial wage you are leaving behind. That match is an immediate, guaranteed return.
Run a monthly check after the windfall is deployed.
A lump-sum payment changes your minimum payment amounts and potentially your credit utilization. Reviewing your balances the following month confirms the payment posted correctly and shows how much interest you are saving going forward. The monthly financial audit checklist covers what to review.
This article is for general informational purposes only and does not constitute personalized financial, tax, or legal advice. Consult a licensed financial professional for guidance tailored to your situation.
Starting points you can act on today
You do not need to wait for money to arrive to prepare for it. The three actions below take less than an hour and put you in a position to make a clear decision the moment a windfall appears.
Readers who want a broader habit to anchor this kind of deliberate decision-making can review practical everyday money habits that reduce reactive spending over time.