

Key Takeaways
- Every dollar of income is assigned to a category before the month starts, with nothing left unaccounted for.
- Zero does not mean spending everything; savings and debt payments count as assigned categories.
- The method works whether you use a spreadsheet, an app, or pencil and paper.
- It requires revisiting and adjusting the plan mid-month when actual spending differs from the plan.
- Understanding your spending categories before building the budget is the necessary first step.
Zero-based budget
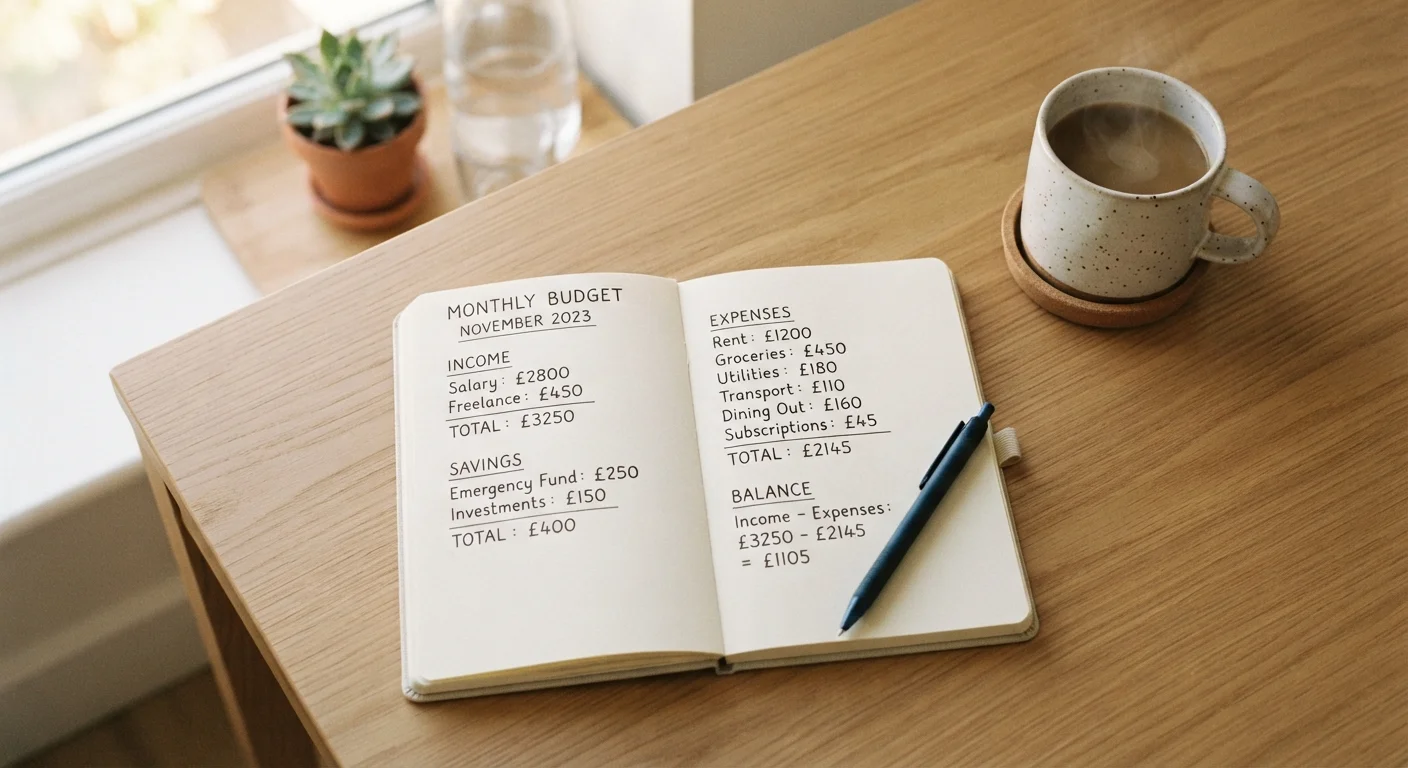
A zero-based budget is a method where you assign every dollar of your income to a specific purpose, so that income minus all your planned spending, saving, and debt payments equals zero. That zero does not mean you have nothing left; it means every dollar has a job. You plan categories like rent, groceries, savings, and entertainment until the total matches your income exactly.
The term comes from zero-based budgeting in corporate finance, where departments justify every expense from scratch each period rather than rolling forward a previous budget. The personal finance version follows the same logic at the household level.
What 'every dollar has a job' actually means
The phrase sounds abstract until you see it in numbers. Suppose your take-home pay is $3,400 this month. A zero-based budget means you sit down before the month starts and write out categories until those categories add up to exactly $3,400.
Rent: $1,100. Groceries: $350. Utilities: $120. Car payment: $280. Gas: $80. Phone: $60. Minimum debt payment: $150. Emergency fund contribution: $200. Entertainment: $100. Clothing: $60. Personal care: $50. That leaves $850. You then keep assigning until the remaining amount is zero.
Those last dollars might go to a vacation savings fund, a pet care reserve, or extra toward a credit card balance. The point is that you decide in advance, not at the end of the month when the money is already gone. If you have trouble knowing what categories to use, mapping your spending categories first gives you a clear starting point.
Start with last month's bank statement
Before building your first zero-based budget, pull up last month's transactions and group them by category. This gives you real numbers to work from instead of guesses, and you will likely find categories you forgot to include. A realistic starting budget is far more useful than a theoretical perfect one.
How the process works month to month
Zero-based budgeting is not a one-time setup. Each month is built fresh, which is what separates it from simply tracking spending after the fact.
Step one: total your expected income for the month. For a salaried worker that is straightforward. For someone with variable income, use a conservative estimate based on past months.
Step two: list every category you expect to spend in, and write a dollar amount next to each one. Fixed costs like rent come first. Then variable necessities like groceries and gas. Then savings goals. Then debt payments beyond the minimum if you have room. Then discretionary spending like dining out or streaming subscriptions.
Step three: subtract the category totals from your income. If the result is greater than zero, assign those remaining dollars somewhere. If it is less than zero, trim categories until it balances. The distinction between needs and wants is what guides those trimming decisions.
Step four: track actual spending against the plan throughout the month. When you spend more in one category than planned, you move dollars from another category to cover it. That adjustment is the active part of the method.
74%
Americans living paycheck to paycheck at some point
A 2023 survey by LendingClub and PYMNTS found roughly 74% of consumers have experienced paycheck-to-paycheck periods, pointing to the value of intentional dollar-by-dollar planning.
$1,000+
Average monthly untracked spending per household
Financial planning research has consistently found that households underestimate discretionary spending by hundreds of dollars monthly when they do not use a category-level tracking system.
Where this differs from other budgeting approaches
The 50/30/20 rule divides income into three broad buckets and lets spending within each bucket vary. Zero-based budgeting goes further by requiring a specific number for every individual category. That specificity is both its strength and its demand.
A percentage rule is faster to set up and easier to maintain. Zero-based budgeting catches more detail. Someone using 50/30/20 might notice that their "wants" bucket is over, but not know which category caused it. A zero-based budget shows exactly which line went over, making it easier to adjust the following month.
For people who want to see how cash envelopes or digital accounts compare as tools for following either method, two practical tracking approaches walks through both options. And if hesitation about starting a budget at all comes from a sense that budgets are too rigid or complicated, common budgeting myths addresses those concerns directly.
Common sticking points and how to handle them
The first month is nearly always imperfect. You will forget a category, underestimate groceries, or discover a quarterly subscription you did not plan for. That is normal. The fix is to adjust mid-month rather than abandon the plan.
Irregular expenses are the most common source of friction. Annual car registration, dental appointments, and back-to-school costs do not appear every month. The solution is a sinking fund category: a line item where you set aside a small amount each month so the money is there when the irregular cost arrives.
People with variable income face a different version of the same challenge. Building the budget on a lower income estimate and then assigning surprise dollars when they arrive keeps the zero-based structure without requiring a perfect income forecast.
The goal is not a perfect plan on day one. It is a plan that gets more accurate each month as you learn how your spending actually behaves.
This article is for general informational purposes only and does not constitute personalized financial advice. For guidance tailored to your individual situation, consider speaking with a licensed financial professional.