

Key Takeaways
- A budget does not have to restrict your life; it just shows where your money goes.
- You do not need a perfect income or zero debt to start budgeting.
- Simple methods work as well as complex spreadsheets for most people.
- Budgeting is not a one-time setup; small, regular check-ins are enough.
- Anyone can begin today using only their current income and basic expense categories.
Why myths about budgeting stick around
Budgeting has a reputation problem. Many people associate it with deprivation, complicated spreadsheets, or a skill reserved for people who already have their finances sorted. These associations are understandable but inaccurate, and they stop a lot of people from ever trying.
The myths tend to spread because they contain a grain of familiar feeling. If you have ever tried to follow a rigid spending plan and quit after one bad week, the idea that budgets are punishing feels true. The problem is usually the myth, not the budget itself. Understanding where your money actually goes is the first real step, and it is far simpler than most people expect.
Myth
Budgeting means cutting out everything you enjoy and living on almost nothing.
Fact
A budget is a spending plan, not a punishment. It shows where your money goes so you can decide what matters to you.
The word 'budget' often calls to mind giving up restaurants, entertainment, and small pleasures indefinitely. That picture comes from strict austerity approaches, which are one option but far from the only one. Most practical budgeting methods build in a category for discretionary spending because sustainability depends on it. A plan that leaves no room for enjoyment tends to fail quickly. The goal is awareness and intention, not deprivation. Distinguishing between needs and wants helps you make deliberate choices rather than removing choices altogether.
Myth
You need to earn a good salary before budgeting makes sense.
Fact
Budgeting is more useful on a tight income because every dollar has to work harder.
People with higher incomes can absorb financial mistakes more easily, which sometimes means they get less benefit from tracking closely. At a lower income, knowing exactly what is coming in and going out can prevent overdrafts, late fees, and short-term debt that costs more than the original shortfall. The mechanics of a budget do not change based on income level; only the numbers do. Starting with whatever income you have now is more useful than waiting for a raise that may or may not come.
Myth
You have to pay off all your debt before you can budget properly.
Fact
Debt repayment is a spending category within a budget, not a prerequisite for having one.
Carrying debt is one of the most common reasons people say they feel too financially chaotic to budget. In practice, a budget is the tool that helps manage that chaos. Minimum payments, extra repayments, and the order in which you tackle multiple debts all fit naturally into a spending plan. Waiting until debt is gone before tracking income and expenses means missing the period when careful planning matters most.
Myth
Budgeting requires a complicated spreadsheet and hours of work each week.
Fact
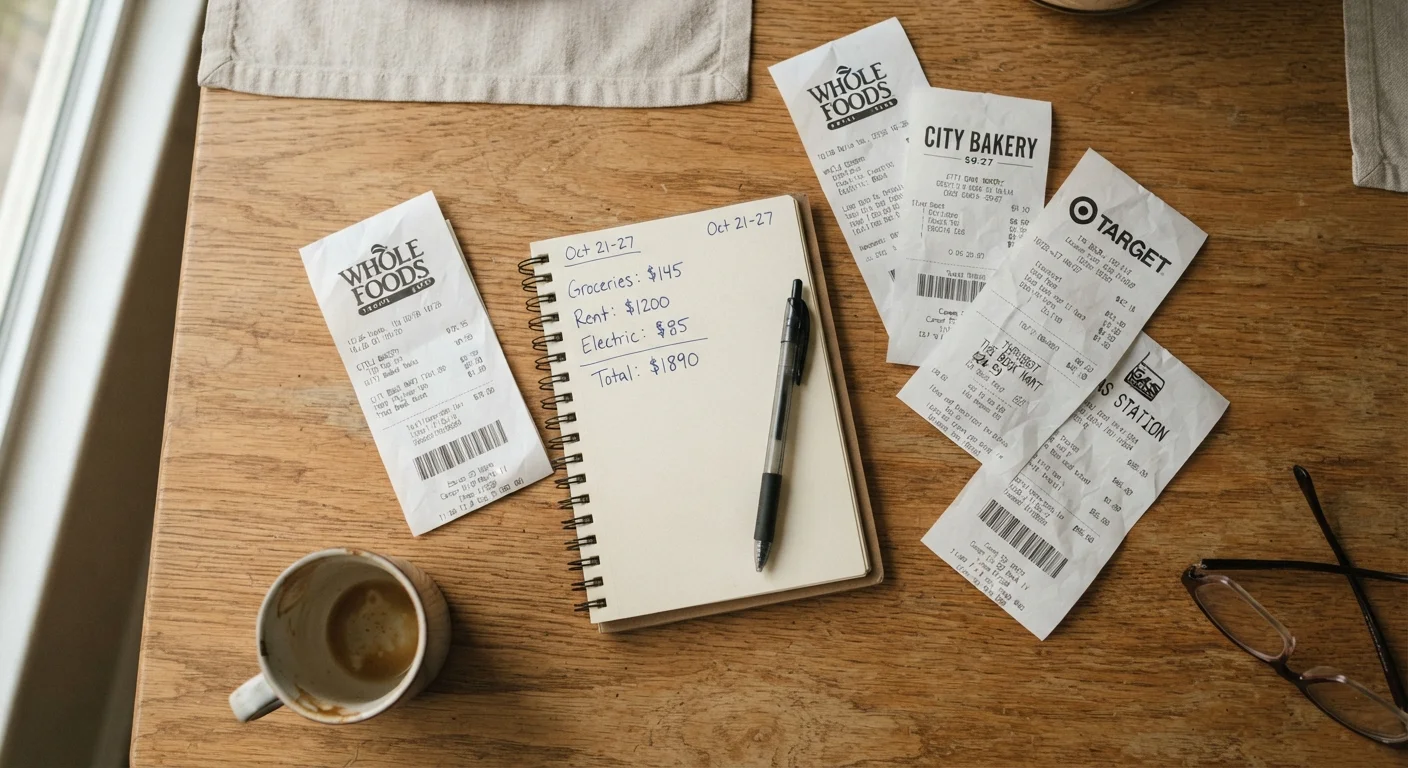
A written list of income and fixed expenses, reviewed monthly, is enough to start.
Spreadsheets, apps, and envelope systems each have their advocates, but none of them is necessary to begin. A piece of paper listing what comes in and what goes out covers the core function. Many people find that a 15-minute monthly review of their bank statement tells them most of what they need to know. Complexity can be added later if it helps, but starting simple is more important than starting with the right tool. The format is secondary to the habit of actually looking at the numbers.
Myth
One bad spending week means the whole budget has failed.
Fact
A budget is a guide, not a contract. Missing a target in one week does not erase the rest of the month.
This belief causes more people to quit budgeting than almost anything else. An unexpected expense, a social occasion, or a moment of impulse spending is treated as evidence that the budget does not work, rather than as a normal variation within a longer pattern. Budgets are adjusted, not abandoned. The habit of returning to the plan after a difficult week is what makes the difference over time, not a streak of perfect compliance.
What a working budget actually looks like
Most functional budgets are not detailed line-item plans reviewed every evening. They are a rough map of income versus spending categories, checked once or twice a month. The 50/30/20 rule is one widely used starting framework: 50% of take-home pay toward needs, 30% toward wants, and 20% toward savings or debt repayment. It is a starting point, not a formula you have to match exactly.
Zero-based budgeting is another option, where every dollar of income is assigned a purpose before the month begins. Both methods work for people with irregular income, fixed salaries, and everything in between. The format matters far less than the habit of looking at the numbers consistently.
Small recurring expenses are often the place where a budget first pays off. Subscriptions, convenience purchases, and automatic renewals can quietly reduce what is available for bigger goals. A simple monthly review catches those before they compound.
This article is for general informational purposes only and does not constitute personalised financial advice. For guidance specific to your circumstances, consider speaking with a licensed financial professional.