
Key Takeaways
- Blockchain is a type of database technology; cryptocurrency is one application that uses it.
- Not all blockchains involve currency, and not all cryptocurrencies rely on a traditional blockchain.
- The confusion largely traces to Bitcoin, which introduced both concepts simultaneously to the public.
- Businesses use blockchain for supply chains, medical records, and contracts without any cryptocurrency involved.
- Understanding the distinction helps readers evaluate news claims and technology decisions more accurately.
How the confusion started
When Bitcoin launched in 2009, it introduced blockchain technology and a new form of digital currency in the same package. For most people who first heard about either concept, the two arrived together, so it felt natural to treat them as the same thing. Tech coverage at the time rarely separated the infrastructure from the application built on top of it, which locked in the conflation early.
Think of it this way: the internet is a network infrastructure, and email is one application that runs on it. Nobody confuses the internet with email. But because blockchain had no pre-existing everyday use that people already understood, cryptocurrency filled that mental slot by default. The result is a persistent myth that has proven difficult to dislodge even as blockchain has moved into industries with no currency involved at all.
Myth
Blockchain and cryptocurrency are the same thing. If you use one, you are using the other.
Fact
Blockchain is a data-recording technology. Cryptocurrency is one type of application that can be built using it.
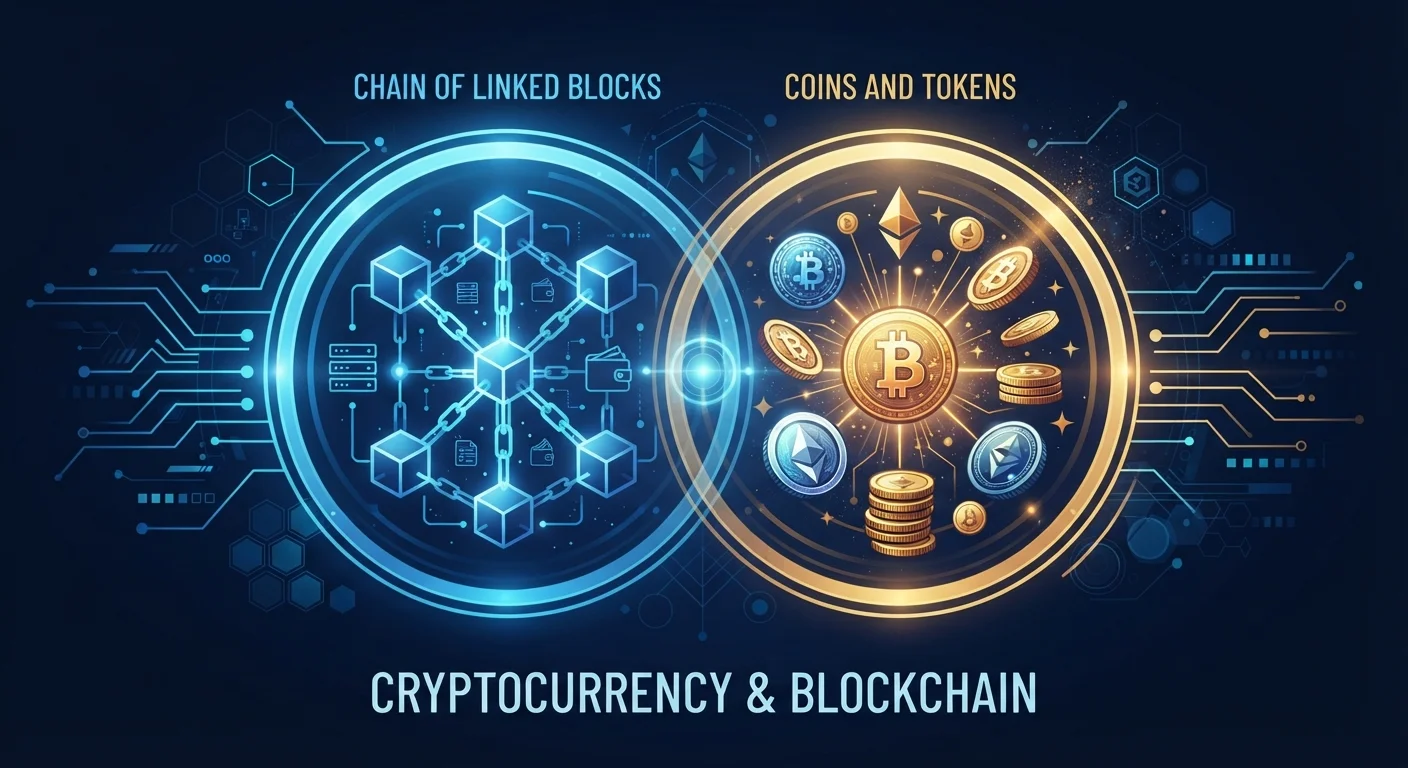
The two concepts share an origin story but they are not interchangeable. A blockchain is a method for storing and verifying records across a distributed network. Cryptocurrency is a digital asset that uses that method to track ownership and prevent fraud. Many blockchain deployments, such as those used in supply chain auditing or medical record systems, carry no cryptocurrency at all.
Myth
All blockchains are public and open for anyone to inspect, like Bitcoin's ledger.
Fact
Blockchains can be public, private, or permissioned, with access controlled by the organization running them.
Public blockchains like Bitcoin's allow anyone to view the full transaction history. Private blockchains restrict read and write access to approved participants only. Permissioned blockchains sit in between, allowing open participation in some functions while gatekeeping others. Many enterprise deployments, in banking and healthcare for example, use private or permissioned configurations precisely because they cannot share sensitive data openly.
Myth
Investing in blockchain technology means buying cryptocurrency.
Fact
Investing in blockchain as a technology and holding cryptocurrency are separate financial activities with different exposures.
Publicly traded technology companies develop blockchain software, sell infrastructure services, and license ledger-based platforms without those products being cryptocurrencies. A person or institution can have financial exposure to blockchain technology through equity in such companies. Holding cryptocurrency is a direct exposure to the price of a digital asset, which carries its own distinct risk profile. The two should not be treated as equivalent in any financial discussion. This article is general educational information and not financial advice; consult a qualified financial professional for guidance specific to your situation.
Myth
If cryptocurrency fails or gets banned, blockchain technology disappears with it.
Fact
Blockchain infrastructure can continue operating in enterprise and government contexts regardless of what happens to public cryptocurrency markets.
Blockchain's core properties, distributed record-keeping and tamper-evident history, are useful independently of whether any particular cryptocurrency retains value or regulatory approval. Regulatory crackdowns on cryptocurrency trading in various jurisdictions have not halted blockchain deployments in logistics, identity verification, or contract management. The technology would persist as long as organizations find the record-keeping model useful, regardless of crypto market conditions.
Myth
Blockchain transactions are completely anonymous, which is why criminals use cryptocurrency.
Fact
Most public blockchains are pseudonymous, not anonymous. Transactions are traceable, and law enforcement agencies regularly use that traceability.
On a public blockchain like Bitcoin's, every transaction is recorded permanently and is visible to anyone. Wallet addresses are strings of characters rather than names, which gives a surface-level impression of anonymity. In practice, once a wallet address is connected to a real identity (through an exchange, a tax record, or other means), the full transaction history for that address becomes an audit trail. Law enforcement agencies and blockchain analytics firms have used this traceability to investigate financial crimes.
What blockchain actually is
A blockchain is a type of distributed ledger: a database that records information across many computers simultaneously. Each batch of records is sealed into a "block," and each block is linked to the one before it through a cryptographic fingerprint. That chain structure makes it extremely difficult to alter past records without changing every subsequent block, which is visible to all participants in the network.
Those properties (distributed storage, tamper-evidence, and transparency) are useful in many contexts. Major shipping companies use blockchain to track cargo across dozens of handoffs. Healthcare organizations use it to maintain patient record chains where every access is logged. Government agencies in several countries have run pilots for land title registries on blockchain to reduce fraud. None of those applications involve sending or receiving cryptocurrency.
Where cryptocurrency fits in
Cryptocurrency is a digital asset designed to function as a medium of exchange, a store of value, or both. Most well-known cryptocurrencies, including Bitcoin and Ethereum, use a blockchain as their underlying record-keeping system because the tamper-resistant, decentralized ledger solves the "double-spend" problem: it prevents the same digital coin from being spent twice without a central bank to police it.
That dependency is real, but it goes only one direction. Cryptocurrency needs some form of distributed ledger to work. Blockchain does not need cryptocurrency to function. The relationship is similar to how a spreadsheet application needs a computer to run, but a computer does not need to run a spreadsheet. For a deeper look at how misunderstood technologies get framed in the press, see this breakdown of quantum computing coverage, which traces a similar pattern of hype outpacing explanation.
Why the distinction matters in practice
Mixing up the two concepts leads to real misreading of news. When a government announces a "blockchain initiative," it often means a record-keeping pilot with no currency element. When a company says it is "exploring blockchain," that claim deserves scrutiny about what specific problem it solves, not automatic association with speculation or digital wallets.
Equally, skepticism about cryptocurrency volatility or regulatory risk does not automatically apply to blockchain as an infrastructure tool. The two have different risk profiles, different regulatory frameworks, and different practical use cases. Someone dismissing all blockchain projects because they distrust crypto is making the same category error as someone who assumes all blockchain projects are investment opportunities.
Separating the concepts is not just an academic exercise. It changes how readers evaluate product announcements, policy news, and job-market trends in the technology sector. The underlying question to ask any time either term appears is simple: is this about the ledger technology itself, or about the assets that run on top of it?